W Residences Sentosa Cove Review 2026: Honest Pros and Cons
Last updated: September 2026 · By Kaeden Ong, Assistant Division Director, ERA Realty Network
See the full The Residences at W Singapore – Sentosa Cove project page — availability elevation chart, unit mix, floor plans, videos and the latest transacted prices, refreshed daily.


.jpeg)

The Residences at W Singapore – Sentosa Cove draws the most polarised opinions of any project I work. One camp sees a hotel-branded waterfront condo at roughly S$1,830 psf, about 40% below its 2010 launch, and calls it the best value in prime Singapore. The other sees 79 years of lease, a developer still holding most of the stock, and a location you reach by car.
Both are looking at real facts. This review scores W Residences Sentosa Cove on eight criteria, lays out pros and cons without softening either, and ends with who should buy and who should walk away. For the full numbers, see the buyer's guide and price history.
The scorecard
| Criterion | Score /5 | One-line reason |
|---|---|---|
| Value at entry | 4.5 | ~S$1,830 psf average vs ~S$2,736 psf at 2010 launch; below Cape Royale's ~S$2,250 and far below CCR new launches at S$3,000+ |
| Brand and services | 4 | Only hotel-branded residence in Sentosa Cove; concierge, room service, AWAY Spa as marketed, though the menu and charges must be confirmed |
| Density and layout | 4 | 228 units in 7 six-storey blocks on ~250,407 sq ft; genuinely low-rise, with 243 car park lots |
| Views | 3 | Marina frontage is excellent, but six storeys means far fewer elevated sea-view units than the towers next door |
| Rental yield | 4 | Roughly 3.5–3.6% gross, higher than most prime condos; 3BR median ~S$11,200 a month |
| Lease | 2.5 | 99 years from 31 Oct 2006, ~79 years remaining; oldest lease start among the projects most buyers shortlist |
| Liquidity and exit | 2 | Thin resale volume, 7.5% foreign buyers, and a developer holding a large unsold stock that competes with you on exit |
| Connectivity | 2 | No MRT; HarbourFront 10–15 min by car, public transport 40–50 min to the mainland |
| Overall | 3.3 | A well-priced lifestyle asset with structural exit risks buyers must price in |
Where the price is today
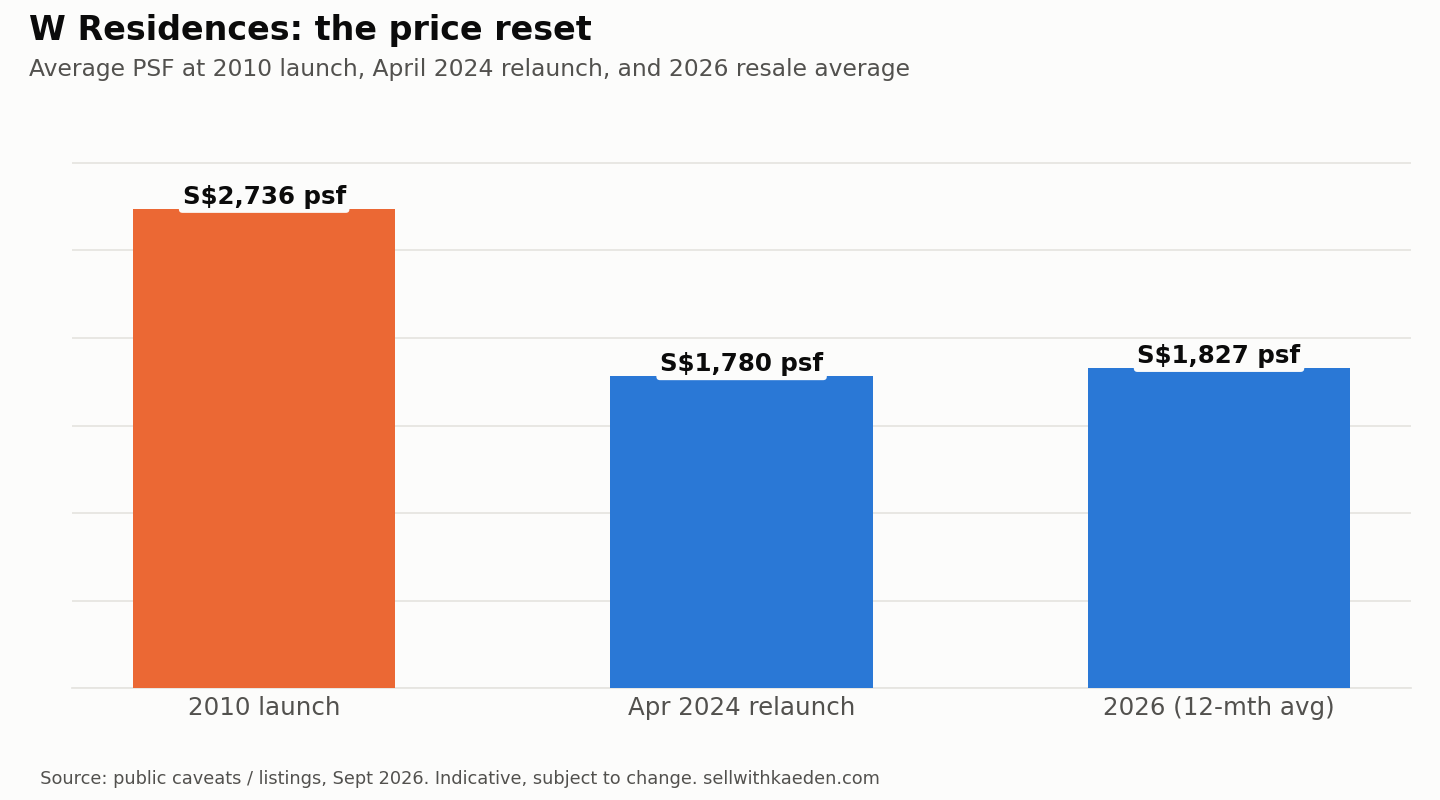
In one paragraph: W Residences launched in 2010 at about S$2,736 psf, peaked at S$2,968 psf that April, then sat largely unsold for over a decade inside a CDL private investment platform. On 15 April 2024 the developer released 58 of 203 held units at roughly 40% below 2010 pricing; 65 sold in the first week at about S$1,780 psf. The 12-month average has since settled at S$1,827 psf (range ~S$1,738–1,985). Recent caveats include a 1,948 sq ft 3-bedder at S$3.39m (S$1,738 psf) in March 2026 and a 3,273 sq ft 4-bedder at S$5.79m (S$1,768 psf) in April 2026.
The pros
1. The price reset is real value, not a discount gimmick
At ~S$1,830 psf you are buying a branded waterfront condo below the Sentosa Cove 99-year average of S$1,899 psf (2024) and roughly S$400 psf below Cape Royale. The 12-month average transaction is about S$3.28m, and no further new residential supply is coming to Sentosa Cove.
2. Brand and services that tenants actually search for
Hotel concierge, room service, housekeeping on request, AWAY Spa access, W hotel rates across Asia Pacific and preferred dining at Quayside Isle, as marketed by the developer (confirm the current menu and charges). The practical effect is a tenant pool that types "W Residences" into the search bar. The branded living guide covers the detail.
3. Low-rise density
Seven blocks of six storeys is rare at this scale. The WET infinity pool has the hotel as its backdrop and there are more car park lots (243) than units. If you dislike lift lobbies and 20-storey stacks, this is the one Sentosa Cove project built the other way.
4. Marina frontage and Quayside Isle next door
Mooring berths on the residences' own promenade, ONE°15 Marina and Sentosa Golf Club minutes away, and Quayside Isle (restaurants, Cold Storage, clinics) directly adjacent. For daily convenience, W is the best-placed project in the Cove.
5. Yield that beats the prime-condo norm
Average rent runs about S$5.4–5.5 psf a month: 2-bedders from around S$7,300, 3-bedders around S$11,200 median, 4-bedders S$11,800–20,000. Gross yield is roughly 3.5–3.6%, versus ~3.1–3.2% at Cape Royale. Full breakdown in the rental yield article.
The cons
1. 79 years of lease
The 99-year lease runs from 31 October 2006, so about 79 years remain (Cape Royale's runs from 2008). A leasehold asset loses value on a curve that steepens with time, and bank and CPF rules tighten as the remaining lease falls. This is a hold-and-enjoy asset, not a land bank for the next generation.
2. Developer overhang sets your resale ceiling
In 2024 the developer held 203 of 228 units and released 58. A large unsold stock remains in the private investment platform, including 17 penthouses unsold in 2024 marketing. The developer said future phases would come at slightly higher psf. That caps what a resale buyer will pay you: why buy your unit when the developer can sell them a first-hand one at a similar number? Until that stock clears, resale pricing is anchored to the developer's list.
3. Low-rise means fewer sea-view units
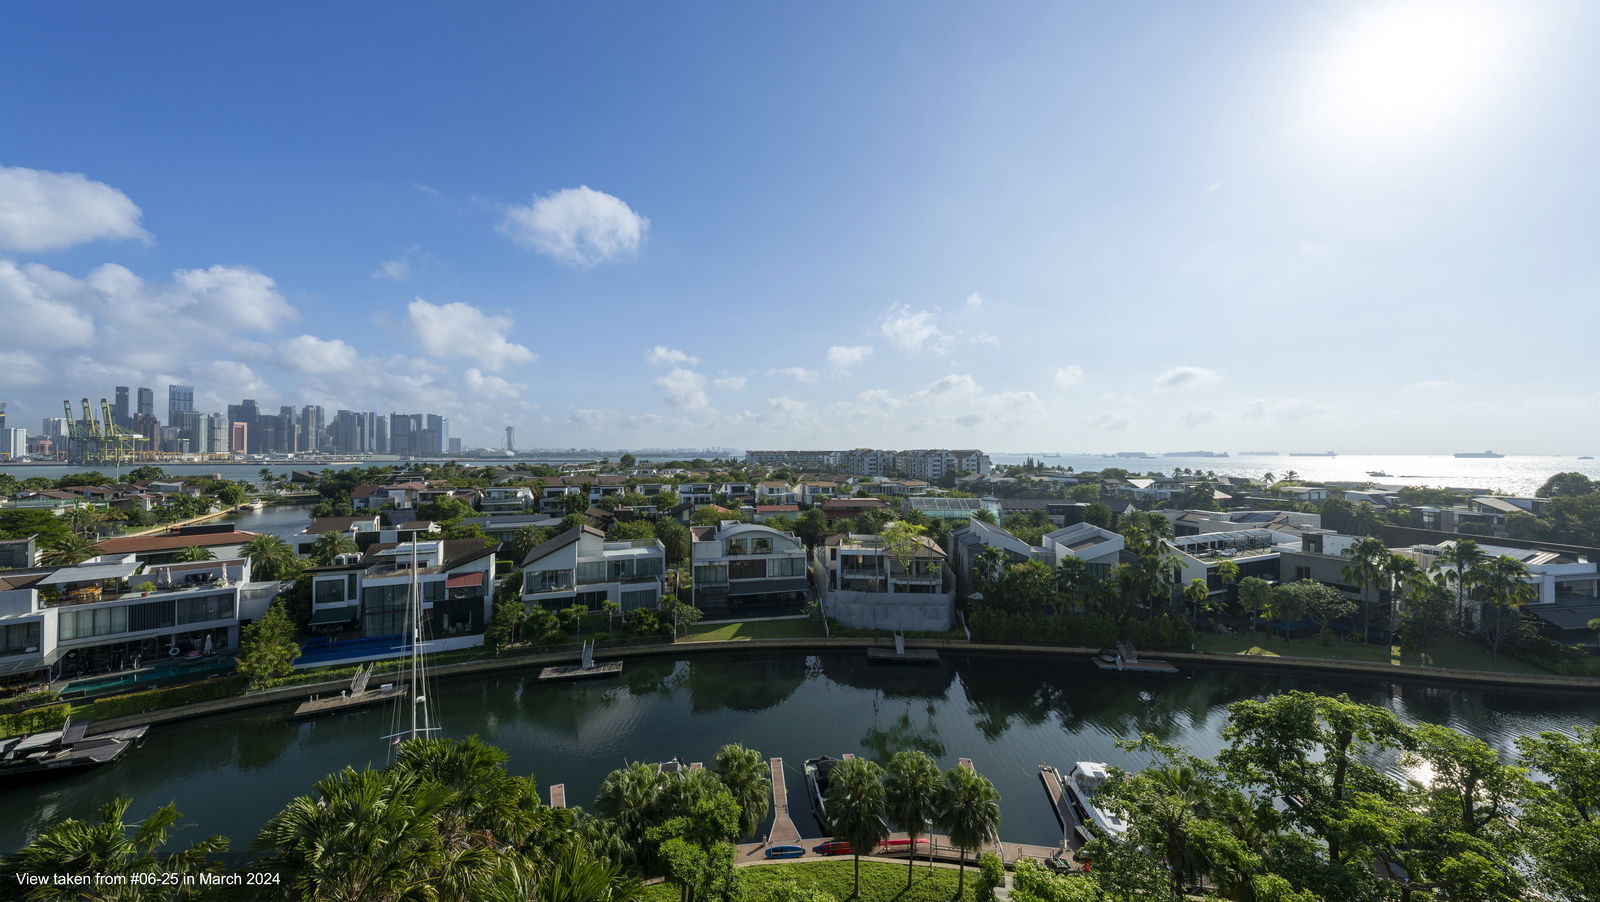
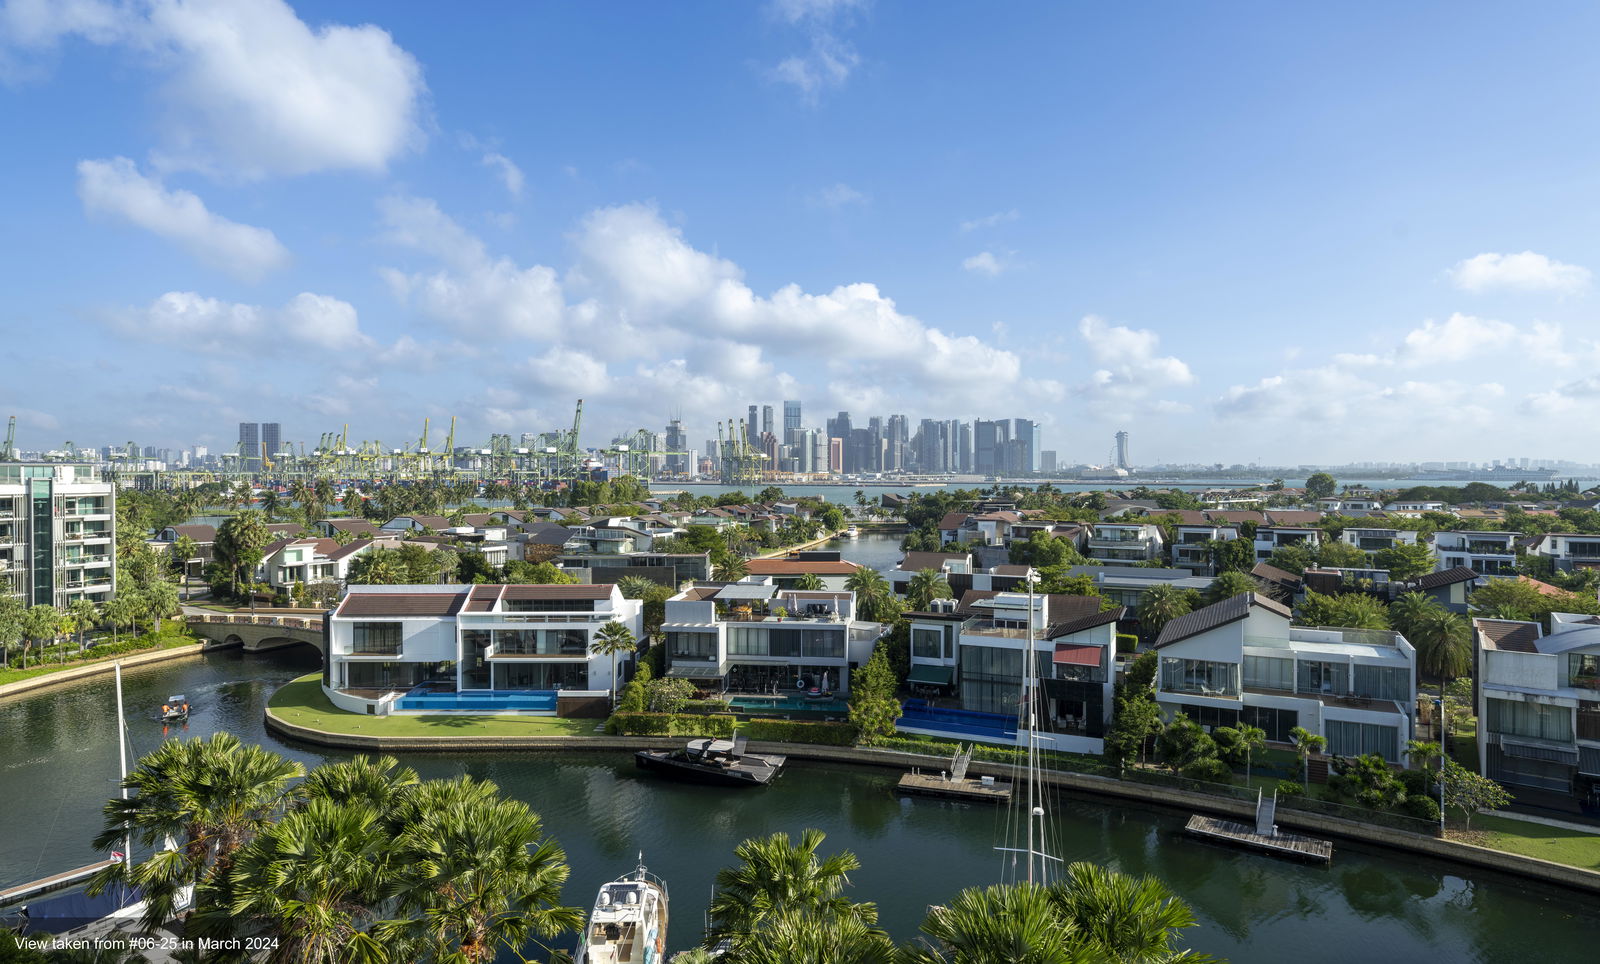
Only the front stacks get open water; inner blocks look at gardens, the pool or each other. Cape Royale's 17–20-storey towers give far more units a sea horizon. If the view is your priority, your choice here is narrow and those units carry a premium. See floor plans and unit types.
4. Car-dependent, with no school on the island past K2
No MRT on Sentosa. HarbourFront MRT is 10–15 minutes by car, the CBD 15–20, public transport to the mainland 40–50 minutes. Islander Pre-School by EtonHouse covers up to K2; after that it's a daily drive.
5. Thin foreign demand
Caveats show 61.6% Singaporean, 28.8% PR, 7.5% foreigner and 2.1% company buyers; the 2024 relaunch was 94% SC/PR. With 60% ABSD, the international buyer branded residences are designed for is largely absent. Your future buyer is a local upgrader, not a global collector, and that changes how the brand premium is valued at exit.
6. Thin liquidity
Sentosa Cove trades in low volumes, and W lower still because the developer, not the resale market, is the main seller. Pricing looks stable partly because there are few forced sellers. Plan for a long marketing period on exit. With the 4-year SSD at 16/12/8/4%, this is a five-year-plus commitment.
Yield in context
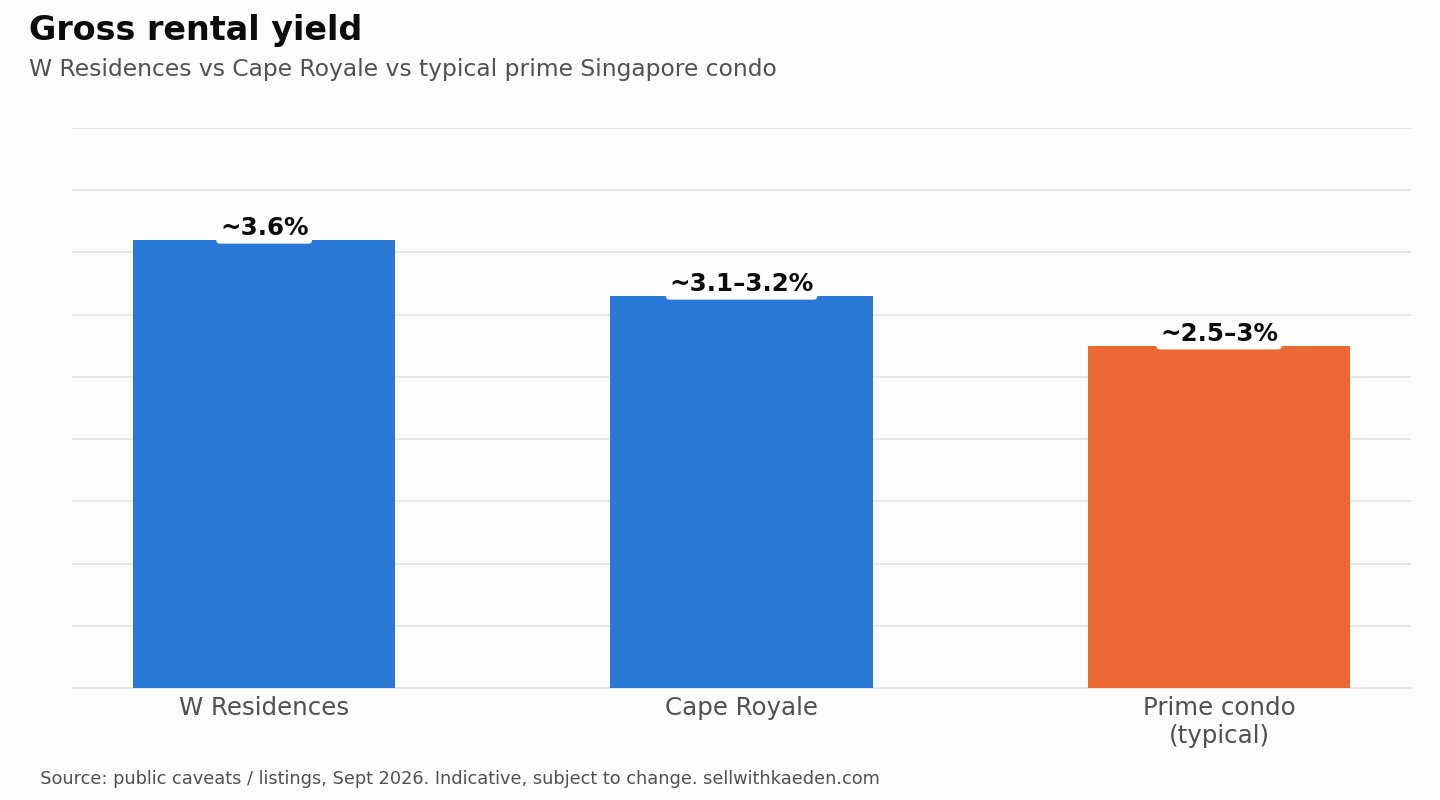
The yield advantage exists because the price fell and the rents didn't. The investment analysis tests whether that survives the exit problem.
Who should buy W Residences
- Owner-occupiers who can hold 7–10 years. A branded waterfront home at a psf the mainland can't offer; the exit ceiling matters less if you aren't selling into it.
- Yield-first investors with patient capital. Roughly 3.5–3.6% gross and a reset purchase price. Accept that growth is capped while the developer is still selling.
- SC, PR or FTA-national buyers (US, Switzerland, Norway, Iceland, Liechtenstein). At 0–5% ABSD the maths works; at 60% it usually doesn't. See the foreigner and ABSD guide.
- Boat owners and frequent travellers. Berths, concierge, lock-and-leave.
Who should not buy
- Anyone with a sub-five-year horizon. SSD, thin liquidity and developer competition on exit make short holds a losing proposition.
- View-first buyers. Cape Royale gives you more sea-view stacks for about S$400 psf more; decide which matters.
- Families needing a school run without a second driver.
- Buyers who need the brand to deliver capital growth. It didn't between 2010 and 2024. Buy the price, not the badge.
Verdict
W Residences in 2026 is a good home at a fair price with a hard exit: 3.3 out of 5 as an asset, higher as a place to live. Buy for space, brand, marina, yield and a long hold, and the cons are manageable. Buy expecting the 2010 psf to return, and the developer's own unsold stock is the first thing in your way.
Frequently asked questions
Is W Residences Sentosa Cove worth buying in 2026? For owner-occupiers and yield investors with a five-year-plus horizon, yes: ~S$1,830 psf is about 40% below the 2010 launch and the yield is roughly 3.5–3.6%. It is a poor fit for short holds or view-first buyers.
What are the main drawbacks of W Residences? A 99-year lease from 2006 (~79 years left), a large developer-held unsold stock that caps resale pricing, fewer sea-view units because of the six-storey height, car dependence and thin liquidity.
Why is W Residences cheaper than Cape Royale? Older lease start, low-rise design with fewer view units, and a developer relaunch in April 2024 at ~40% below 2010 pricing. W averages ~S$1,830 psf versus Cape Royale's ~S$2,250.
How many units are still unsold at W Residences? The developer held 203 of 228 units in 2024 and released 58 at the relaunch. A significant stock remains in a CDL private investment platform; ask for the current figure.
What is the rental yield at W Residences? Roughly 3.5–3.6% gross, with 3-bedders renting around S$11,200 a month and average rents of about S$5.4–5.5 psf per month.
Who buys at W Residences? Caveats show 61.6% Singaporean, 28.8% PR, 7.5% foreigner and 2.1% company buyers. The April 2024 relaunch was 94% SC/PR.
Ready to look at W Residences?
I work Sentosa Cove daily and keep a live comparison of all 10 non-landed projects on the island — PSF, yield, liquidity and which stacks are quietly available. If you're weighing W Residences against Cape Royale or a mainland alternative, message me and I'll send the comparison sheet before we arrange a viewing.
Kaeden Ong · Assistant Division Director, ERA Realty Network · ERA Top 50 · CEA Reg. L3002382K sellwithkaeden.com · WhatsApp for a same-day reply
Disclaimer: This article is for general information only and is not investment, financial or legal advice. Figures, prices, charts and regulations are drawn from public sources and my own records as of September 2026; they may contain errors, are subject to change without notice, and should be independently verified against URA caveats, IRAS, MAS and the relevant developer or MCST before any decision. Past prices are not a guide to future prices. Please speak to a licensed property agent, banker and lawyer about your own situation.
Any prices or charts shown are subject to change and may not be accurate. For reference only, subject to change, not investment advice.
Disclaimer: All prices, availability, transaction figures, calculations, data and charts on this website are for general information only. They may be delayed, incomplete, inaccurate or changed without notice and must be independently confirmed with the relevant developer, authority or professional adviser. Nothing on this website constitutes financial, legal or investment advice.
← All insights